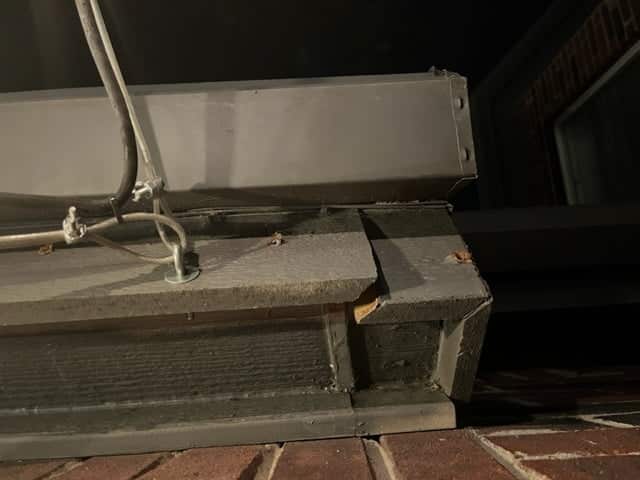
Texas homeowners know that severe weather can arrive with little warning, and hailstorms can leave property owners facing damage that is not always immediately obvious. A storm may pass in minutes, yet its effects can linger through damaged roofing materials, leaks, exterior deterioration, and unexpected repair costs. The situation becomes especially frustrating when an insurance claim is denied, and the homeowner is left questioning whether the insurer fully understood the property’s condition or properly applied the policy. At that point, moving forward requires more than frustration with the decision.
Homeowners need to understand the reasoning behind the denial, examine the coverage involved, and determine whether the available evidence supports a different conclusion. Careful attention to these issues can help distinguish a legitimate coverage limitation from an incomplete investigation or disputed assessment. Barcus Arenas hail damage attorneys in Dallas can help homeowners review a denied claim and understand the legal options available to challenge the insurer’s position.
Read the Denial Letter Carefully
A denial letter usually contains the insurer’s main argument, but every sentence deserves careful review. Homeowners should locate the exact exclusion, limitation, or condition the insurer cited. They should compare that language with the policy’s declarations, endorsements, definitions, and coverage limits. The letter should connect the policy language to the damage suffered by the property. A statement that damage is cosmetic, pre-existing, or unrelated to hail does not resolve every coverage issue. The explanation should match the inspection findings, photographs, repair estimate, and reported storm date.
Preserve Evidence Before Repairs Take Place
Photographs and videos should show the roof, gutters, siding, windows, skylights, vents, fences, air-conditioning equipment, and interior areas affected by leaks. Wide views establish location, while close images capture dents, cracks, stains, and other details. Homeowners should preserve damaged materials when practical. A roofing contractor’s estimate should document repair costs, identify each damaged component, and explain the recommended work. When water enters a home, records should show when the leak began, where it spread, and what temporary measures were taken to limit further damage. Receipts, inspection reports, emails, and call records should remain together.
Test the Insurer’s Stated Reason
Insurers sometimes classify visible dents or deformities as cosmetic damage. That label does not answer whether the condition affects waterproofing, structural performance, service life, or property value. Metal roofing, rooftop equipment, siding, and similar materials require a close inspection rather than a brief visual conclusion. Roof age and material type can become disputed issues. An insurer might blame deterioration when storm evidence points to hail impacts. A qualified engineer, roofing consultant, or other damage professional can compare impact marks, weather records, repair patterns, and the property’s condition before the storm.
Challenge Incomplete Investigations
An insurer’s investigation should address the entire reported loss. If an adjuster inspects only the roof but ignores ceiling stains, insulation, drywall, flooring, or personal property, the claim record is incomplete. The same concern arises when an inspection occurs long after the storm without accounting for temporary repairs or later weather. Homeowners should request the inspection report, photographs, estimate, recorded statements, and other documents supporting the denial. Those materials can reveal missed areas, incorrect measurements, unsupported assumptions, or differences between the adjuster’s notes and the final coverage decision.
Submit a Focused Appeal
An appeal should address the insurer’s stated reasons rather than repeat the original claim. The submission should identify disputed policy language, attach photographs and reports, explain the scope of repairs, and request a written response. A clear timeline should connect the storm, inspection, notice, mitigation work, and denial. Homeowners should follow the policy’s notice and proof-of-loss requirements. They should track all communications and avoid making unsupported statements about the cause or extent of the damage. A complete record gives the insurer less room to rely on confusion or missing information.
Know When Legal Review Makes Sense
Legal review makes sense when the insurer delays communication, refuses to explain its position, relies on a cosmetic-damage exclusion without a complete inspection, or offers less than documented repair costs. Texas Insurance Code § 541 addresses unfair claims handling, including certain improper conduct by insurers. A lawyer can examine the policy, claim file, expert evidence, and correspondence together. That review can clarify whether the dispute involves coverage, valuation, causation, investigation quality, or several issues. Homeowners should seek advice promptly because policies and applicable law can impose deadlines.
Conclusion
A denied hail claim deserves a documented response rather than immediate acceptance. Homeowners should preserve property evidence, obtain the insurer’s supporting materials, compare the denial with the policy, and secure a detailed repair assessment. If the insurer ignored damage or applied an exclusion without adequate support, legal review can clarify the next step. Homeowners should gather the denial letter, policy, photographs, estimates, and claim communications before requesting a case evaluation.